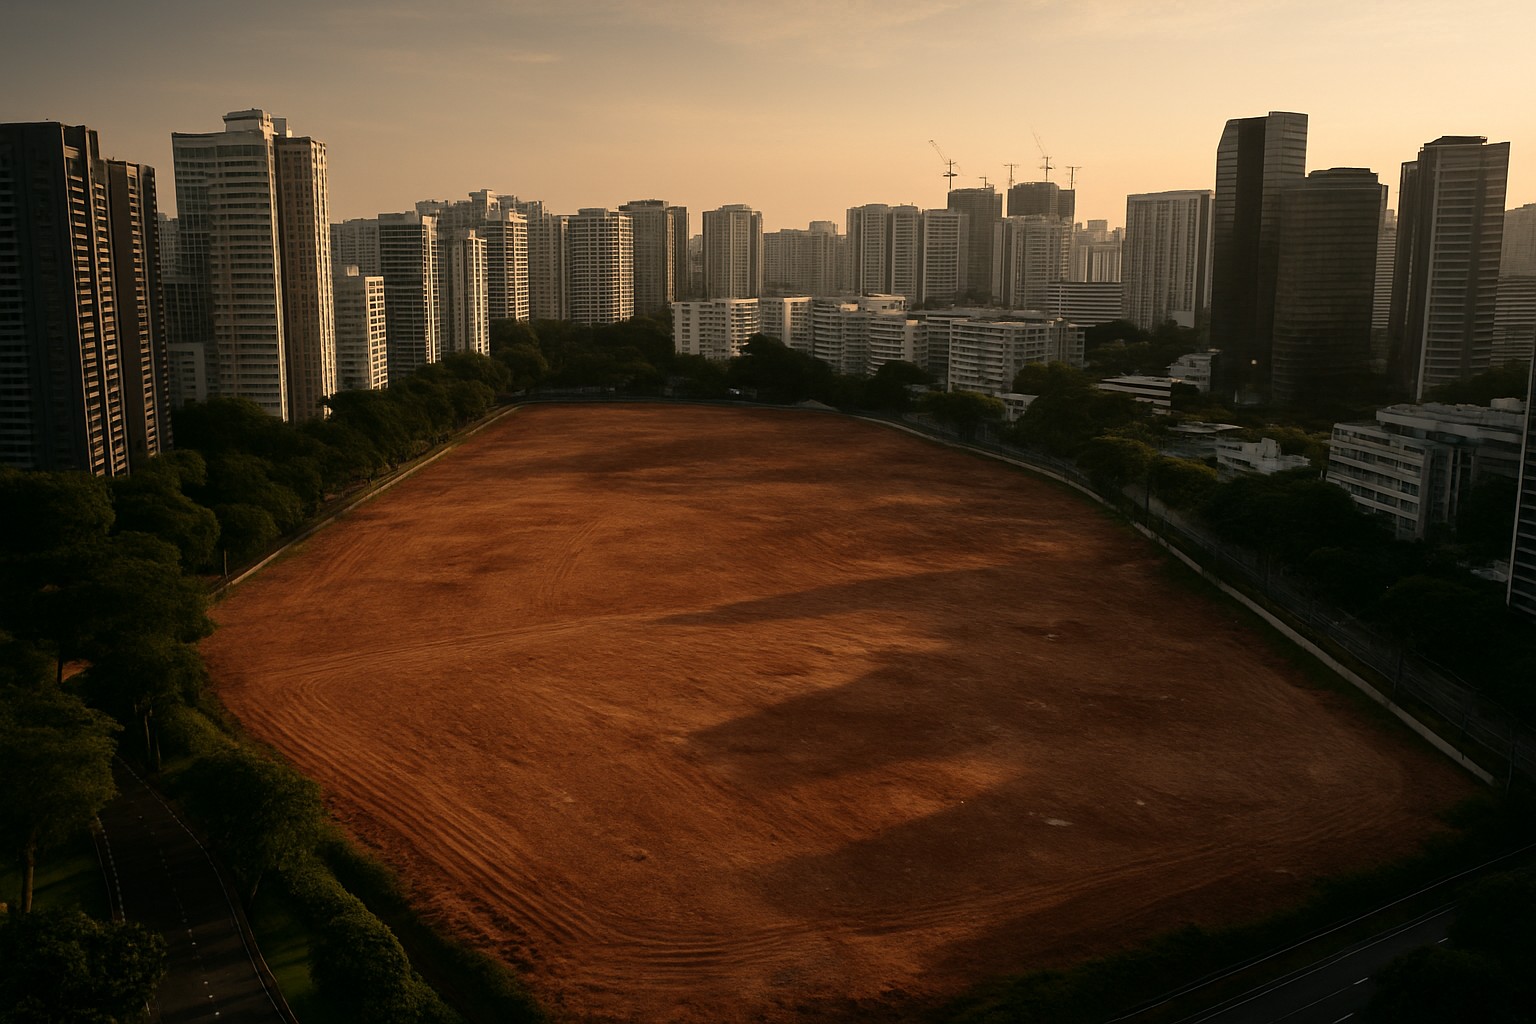
If you own an HDB flat in Bedok, Tampines, or anywhere in the East and you've been thinking about making the move to private property, what just happened at a Government Land Sale tender should get your full attention. This isn't just a developer story. It's a signal about where OCR prices are heading, and it affects every decision you're likely to make in the next 12 to 24 months.
On 1 September 2026, a consortium comprising UOL Group, CapitaLand Development, and SingLand submitted the winning bid for a new residential GLS site at New Upper Changi Road. Their offer came in at S$1.425 billion, translating to S$1,537 per square foot per plot ratio (psf ppr). According to the source research, this sets a new benchmark for a pure residential GLS site in the Outside Central Region.
To put that in context, the nearby Bedok Rise site was awarded just nine months earlier in December 2025 at S$1,330 psf ppr, which itself drew 10 competitive bids. This new bid is 15.6% higher. The winning consortium also beat the next-highest offer from CDL and Hong Realty by 13.8%, a gap that tells you this wasn't a mild outbid. It was a statement.
Pre-tender analyst forecasts from Huttons Asia and Realion ranged between S$1,350 and S$1,500 psf ppr. The actual result cleared even the highest estimate. Based on that land rate, analysts now project eventual launch prices in the range of S$2,900 to S$3,000 psf for a development that will yield 1,010 residential units on a 331,198 sq ft site.
In my view, the 13.8% gap between the winning bid and the second-highest offer is the most telling number here. When that gap is large, it usually means the winner made a strategic call that the rest of the market wasn't fully pricing in. UOL, CapitaLand, and SingLand have committed over S$3.1 billion across multiple major residential sites since late 2025. These aren't companies making guesses. They have conviction in where East Singapore demand is heading.
What I'm seeing on the ground is a developer land-banking urgency that I haven't seen this sharp in quite a few years. The Bedok and East Coast corridor has a genuine demand story behind it. Over 9,500 HDB flats in the Bedok and Tampines vicinity, with nearly 2,300 flats in the immediate area reaching their Minimum Occupation Period between 2022 and 2026. That's a ready upgrader pool, and the developers know it.
Here's the thing most people miss. When analysts underestimate the top bid by S$37 to S$187 psf ppr, it usually means the new benchmark catches the resale market off guard too. Existing District 16 condo owners who've been waiting for the "right time" to sell are now sitting on better negotiating leverage than they realise. At the same time, anyone waiting for OCR new launch prices to soften needs to honestly reconsider that plan.
HDB upgraders in the East: The math is getting harder to ignore. The median resale price for a five-room HDB flat under 15 years old was around S$1.03 million in 2025, with four-room flats at approximately S$860,000, based on the source research. A mid-sized unit at this new development at S$2,900 psf could easily hit S$2.9 million or more. After your HDB sale proceeds, you're looking at a financing gap of S$1.8 million to S$2.1 million before grants. That's a real number you need to model carefully with a mortgage before you fall in love with any unit. The window to enter at lower quantum is getting narrower, not wider, but the entry point still needs to fit your actual financial position.
Existing condo owners in Bedok and the East Coast corridor: A new land benchmark generally lifts the pricing floor for resale units in the same submarket. If you're a seller, this gives you firmer ground in negotiations right now, before the new supply from this project and the surrounding Bayshore pipeline hits the market. Once this development launches and over 3,000 new units across Vela Bay, Bayshore, Bedok Rise, and this site compete for the same upgrader pool, the resale market may face a temporary demand diversion. Timing your exit well matters.
Private property investors watching the East: The yield math gets tighter at S$2,900 to S$3,000 psf. Typical gross yields in the OCR run between 3.0% and 3.8%, and at these quantum levels, you'd need strong rental demand to justify a pure investment case. The capital appreciation story may still hold if the Bedok/East Coast corridor continues to reprice upward, but investors should go in eyes open about the yield compression reality. The pipeline concentration of over 3,000 units in one submarket is also worth monitoring closely for absorption risk at launch.
S$1,537 psf ppr is not just a developer statistic. It's a structural repricing event for OCR residential land, and it will flow directly into launch prices, resale benchmarks, and the affordability calculations of every HDB upgrader in the East. The Bedok corridor has real demand fundamentals behind it, but the entry price has moved up decisively. Whether you're thinking about upgrading, selling, or investing in this part of Singapore, the decision you make in the next 12 months will look very different from the one you could have made a year ago. If you want to run through the numbers specific to your situation, I'm happy to do that with you. WhatsApp me at +65 9750 1055 or visit keithtanboonkee.com to get started.
25 years experience · 1,000+ transactions · 4,379 TOP units managed
💬 WhatsApp Me