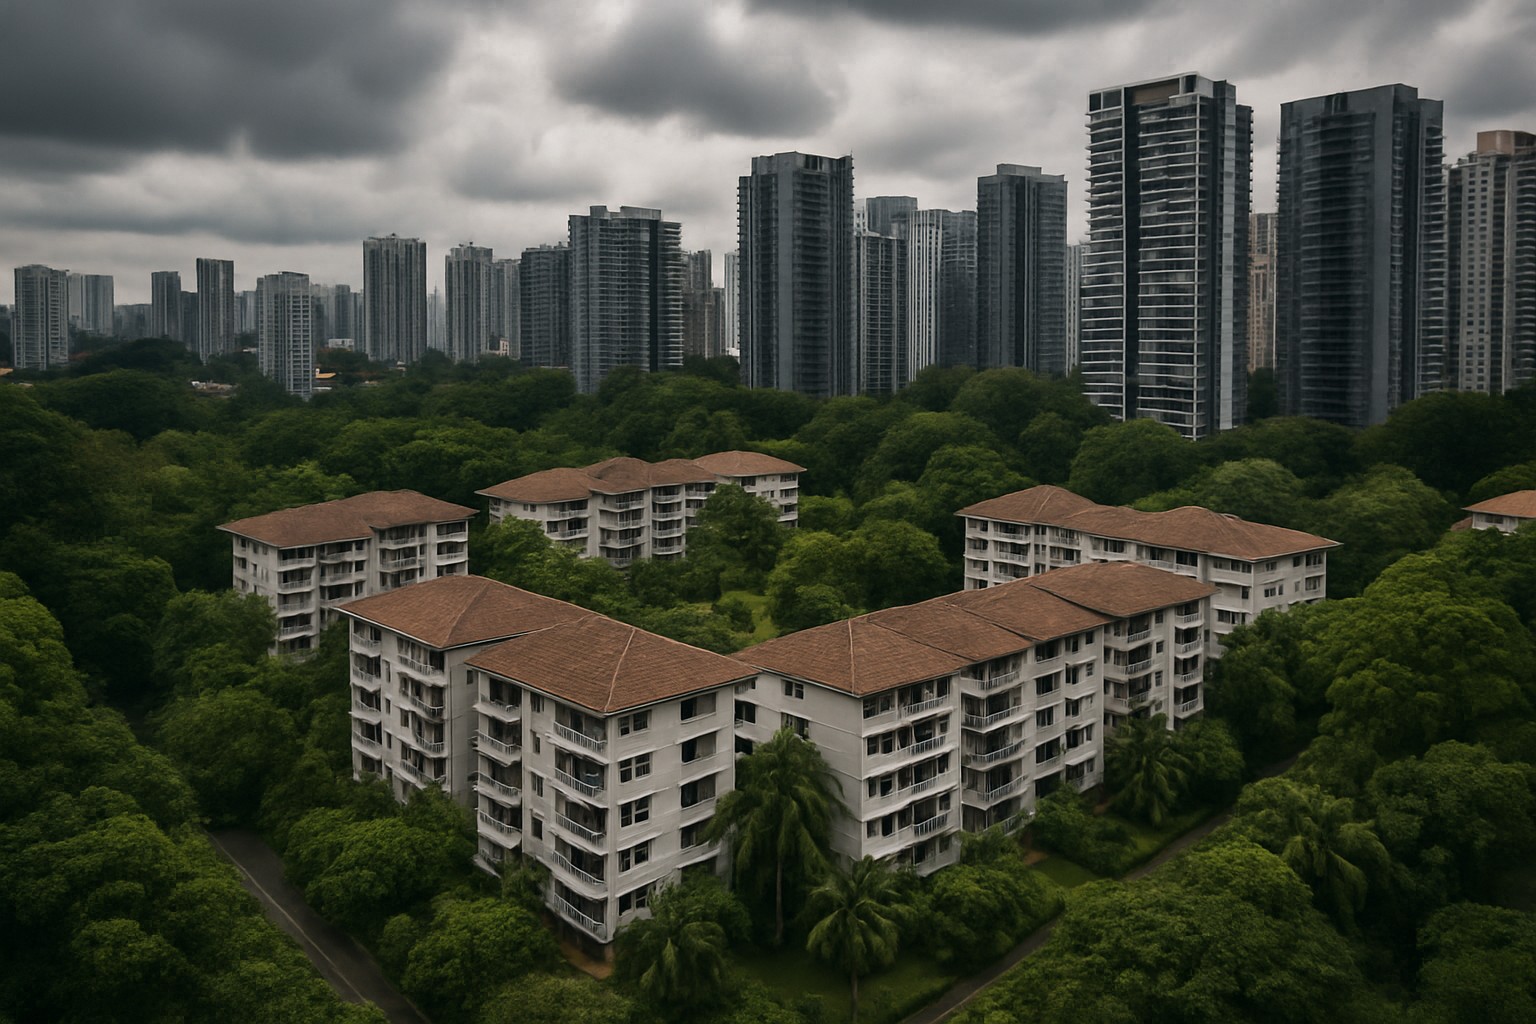
If you own a unit at Gilstead Court, or if you've been watching the en bloc market in Singapore hoping for signs of life, this week's news is worth your full attention. A fourth attempt at collective sale is now live, and the numbers behind it tell you something meaningful about where the CCR market is heading and whether developer appetite has finally caught up with owner expectations.
According to The Business Times, Gilstead Court has been relaunched for collective sale at a reserve price of S$198 million, with JLL as marketing agent. That works out to approximately S$1,874 psf per plot ratio (psf ppr) on the base gross floor area, or S$1,751 psf ppr when the 7% bonus balcony gross floor area is factored in. For context, the site sits on Gilstead Road in the Novena area, comprising 48 apartments across three four-storey blocks.
Under the 2025 Master Plan, the 7,012 sqm site is zoned Residential at a gross plot ratio of 1.4. JLL's Nicholas Ng, Head of Land and Collective Sales, noted that no land betterment charge is payable even with the additional bonus gross floor area included, which is a genuine cost advantage for any acquiring developer. Subject to URA approval, the site can potentially be redeveloped into a five-storey boutique development of up to 98 apartments at 100 sqm each.
This is the fourth time the owners have tried. The first attempt in June 2018 was launched at S$168 million (S$1,590 psf ppr) and closed in July 2018 with no bids. A second attempt in January 2019 was repriced down to S$153 million (S$1,448 psf ppr) and also failed. A third attempt around 2022 to 2023 similarly found no takers. Now owners are coming back at S$198 million, which is nearly 30% above the 2019 reduced price. The question is whether the market has finally moved enough to meet them.
In my view, the jump to S$198 million is bold, but it's not irrational. What I'm seeing on the ground is that new launches in the CCR, particularly in District 11, are transacting at S$2,800 to S$3,500 psf and above. At that prevailing launch price level, a land cost of S$1,874 psf ppr starts to pencil out for a developer with a clean project structure, which is exactly what Gilstead Court offers. Freehold tenure, no LBC, and a boutique scale that keeps sales risk manageable.
Here's the thing most people miss about this story. Four failed attempts doesn't necessarily mean the asset is unmarketable. It means the timing was wrong each time. The 2018 cooling measures crushed developer appetite overnight. High interest rates in 2022 to 2024 made acquisition financing expensive. Now you have rates coming down, developer land banks thinning out, and GLS competition staying fierce. The conditions for an en bloc transaction in CCR are genuinely better today than they have been since 2017.
That said, I want to be honest about the risk. The step-up to S$198 million narrows the pool of developers who can underwrite this. When you add the 35% developer ABSD on residential land, you're looking at roughly S$69 million in ABSD alone on top of the acquisition price. Total project cost could approach S$330 million to S$350 million or more by the time you factor in construction and marketing. The developer's break-even ASP on 98 units is roughly S$3,100 to S$3,400 psf. That's achievable in Novena today, but it leaves limited cushion if the market softens. Developers know this too.
If you are one of the 48 owners at Gilstead Court, the estimated average payout per unit if the sale succeeds is around S$4.1 million, calculated on an unweighted basis across the reserve price. Based on current individual resale values for comparable freehold units of this size in the area, that represents a meaningful premium above what you'd likely achieve selling on the open market. The no-LBC structure is a genuine selling point to emphasise to prospective developer buyers. But I'd encourage the collective sale committee to be realistic: four attempts at escalating prices suggest that the gap between owner expectations and developer underwriting has historically been the sticking point, not the quality of the site.
If you're a private condo investor or buyer watching this space, pay attention to what happens here. If Gilstead Court successfully transacts, it would be one of the clearest signals that the CCR en bloc market has reawakened after years of dormancy. A new boutique freehold launch in Novena at likely S$3,000 psf and above adds a fresh comparable to the District 11 pricing landscape. Existing owners in nearby developments along Gilstead Road and the broader Novena corridor could see their own asset valuations nudged upward as a result. That's worth tracking even if you have no direct connection to this site.
For investors considering CCR exposure more broadly, rental yields in this segment typically run at 2.0% to 2.8% at current price points. The capital appreciation thesis in CCR relies on continued price growth at the upper end of the market, which has been broadly supported but is more sensitive to macroeconomic shifts than the OCR and RCR segments. If you're evaluating whether a future new launch on this site makes sense as an investment, watch the tender outcome closely. A successful transaction at or near reserve price tells you developers are confident enough in Novena pricing to make the numbers work, which is a meaningful signal about where launch prices are headed.
Gilstead Court's fourth en bloc attempt at S$198 million is one of the most watched collective sale tests in Singapore right now. The fundamentals supporting this attempt are the strongest they've been across all four tries: freehold tenure, zero LBC, a boutique development profile, improving rate conditions, and CCR launch prices that can absorb the land cost. Whether a developer agrees is still an open question, and the ABSD burden on residential land acquisitions means the hurdle is high. If this one closes successfully, it signals something real about where the CCR market is heading. If it doesn't, owners will face a difficult conversation about what the true market value of a collective exit actually looks like in 2025. Either way, this outcome matters to anyone with CCR exposure or en bloc ambitions of their own. If you want to talk through how this affects your own property decisions, I'm happy to have that conversation with you directly. WhatsApp me at +65 9750 1055 or visit keithtanboonkee.com to find out more.
25 years experience · 1,000+ transactions · 4,379 TOP units managed
💬 WhatsApp Me